VA home loans
Your VA benefit
was earned.
Let's put it to work.
VA financing can offer powerful homebuying benefits for eligible veterans, active-duty service members, and military families.
Eileen helps make the process clear from the first conversation through closing.
Call today to start your VA home loan plan.
714.362.6087Clear guidance. Personal support. VA-focused financing.
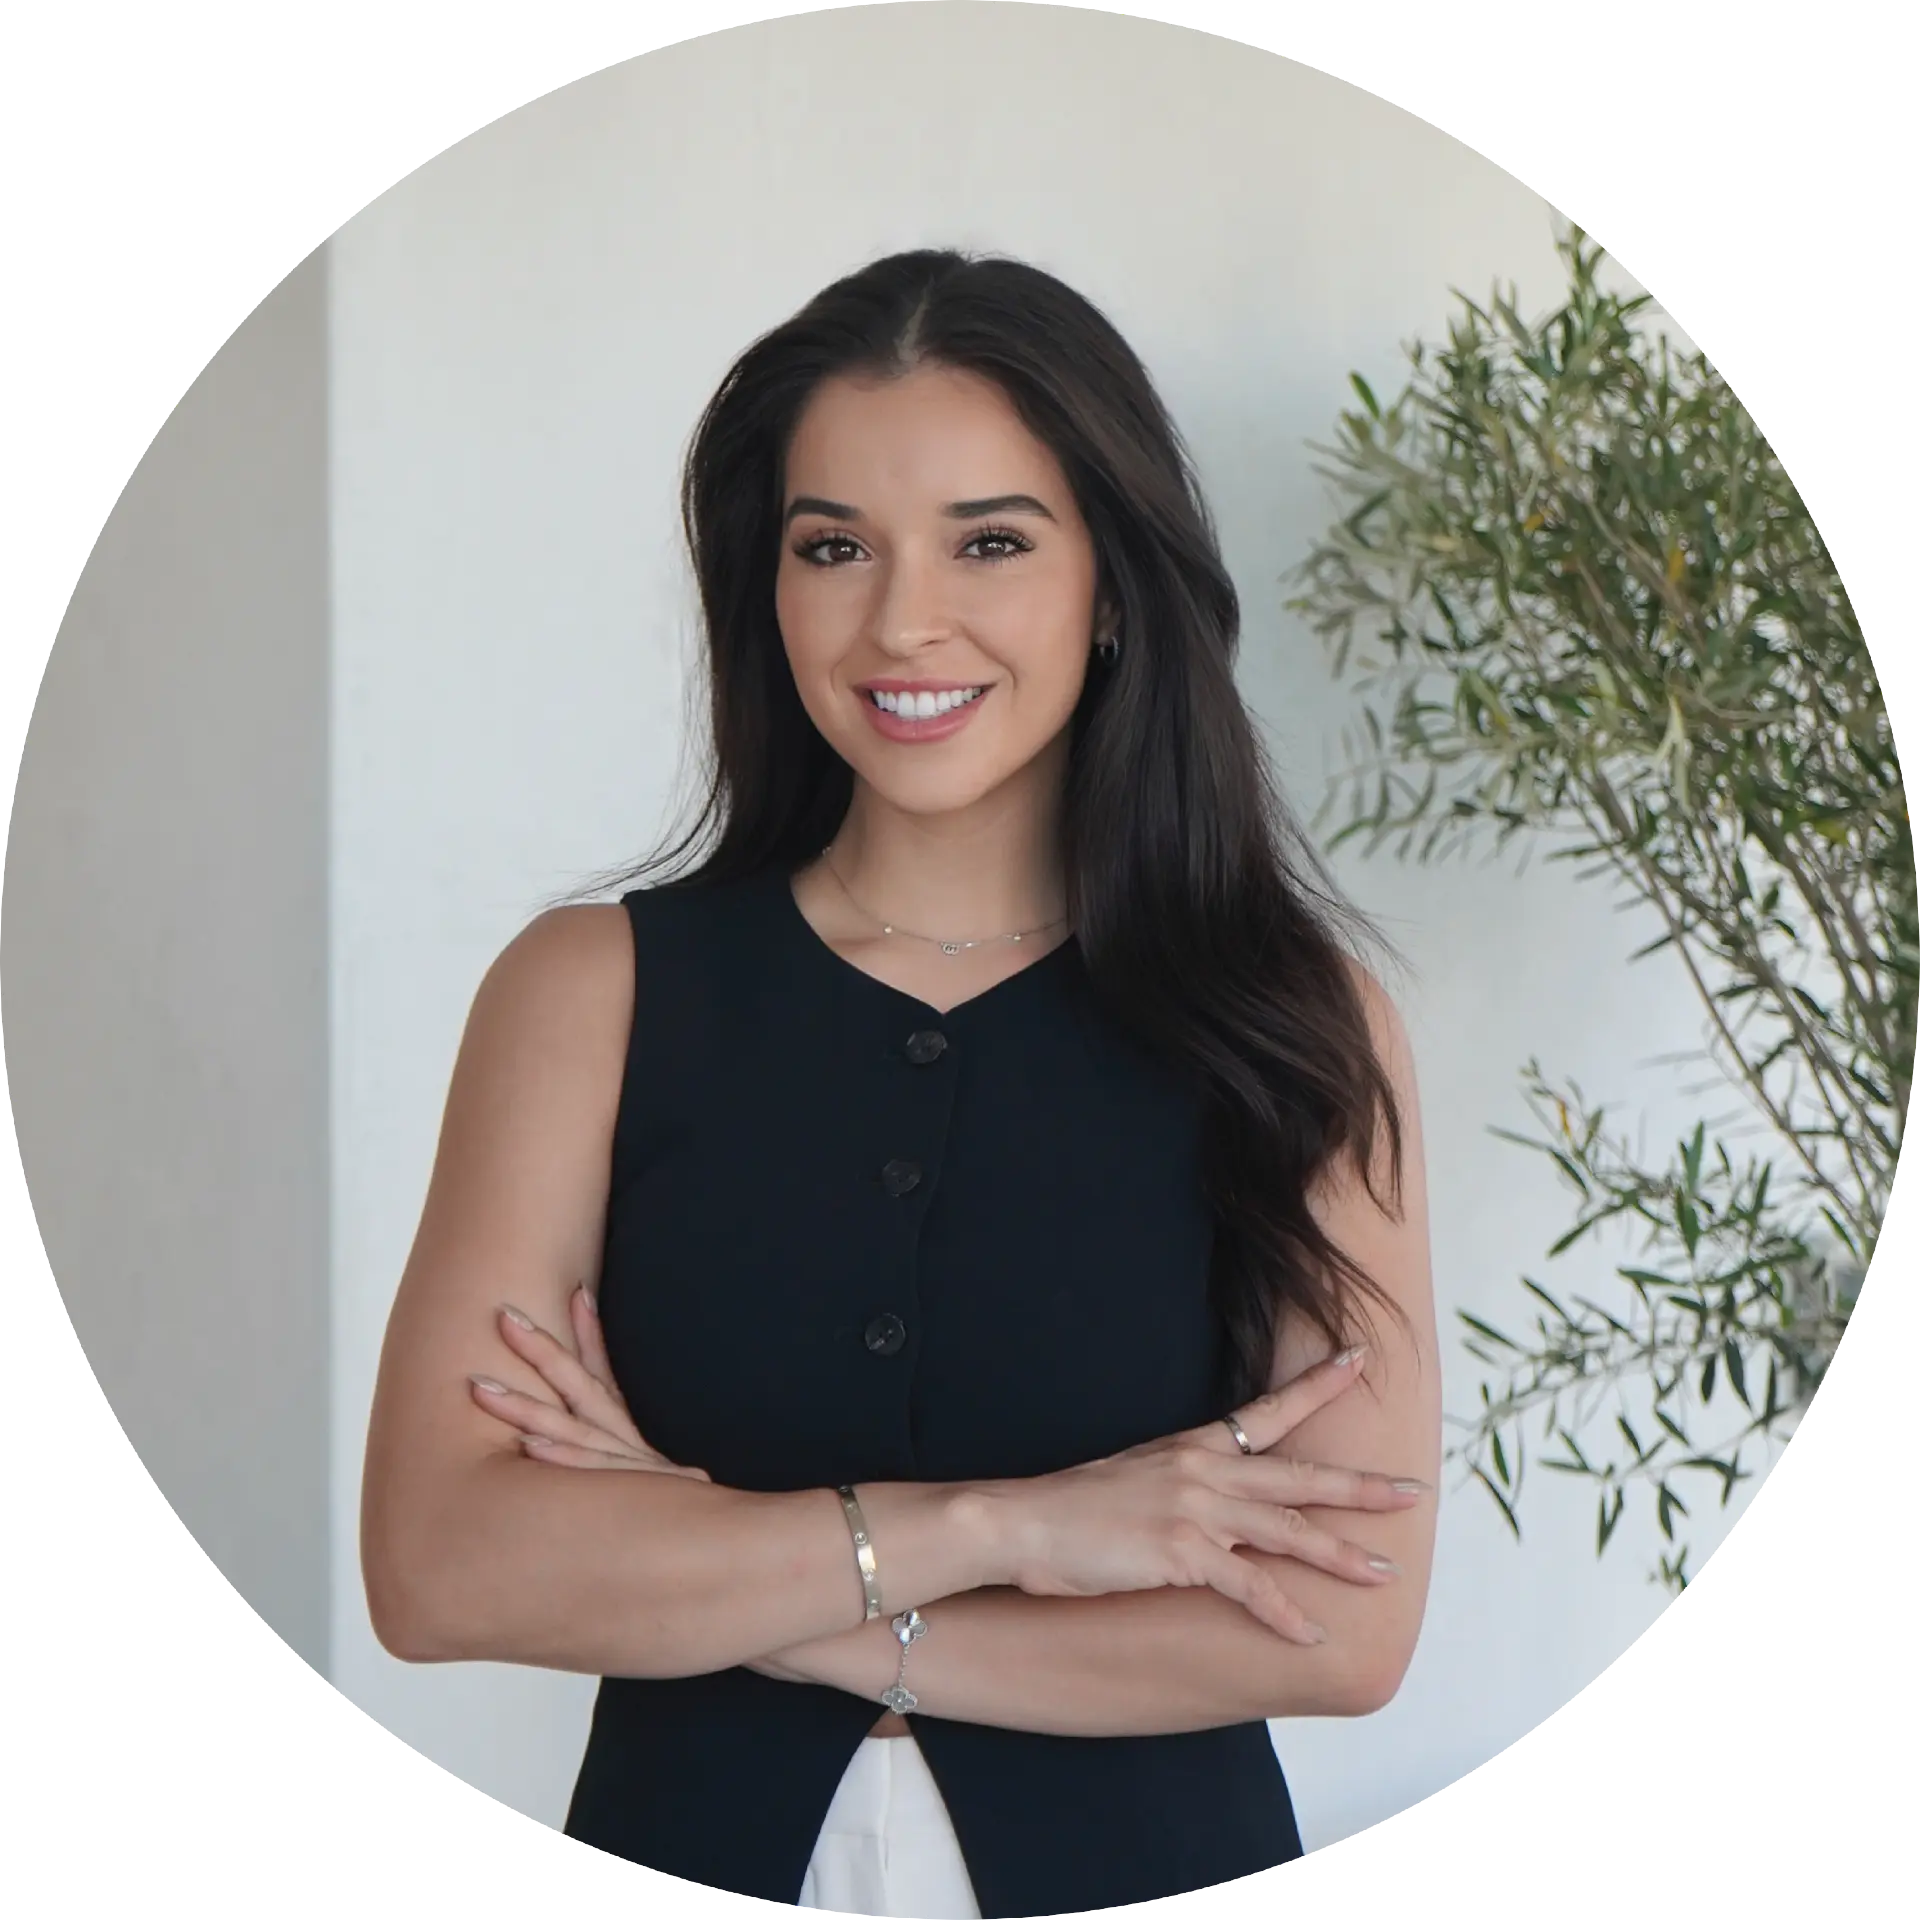
Eileen Mirabal
Loan Officer
NMLS 1587467
VA home loan guidance, made simple.
Your VA benefit may be more powerful than you think.
Scroll to see how $0 down, no monthly PMI, seller credits, and the right strategy can change the numbers.
The VA advantage
One of the strongest homebuying benefits available.
For eligible borrowers, VA financing can provide advantages that conventional financing may not.
Potential for $0 down
Eligible VA buyers may be able to purchase without a traditional down payment.
No monthly private mortgage insurance
VA loans generally do not require monthly private mortgage insurance.
Competitive financing
VA-backed financing can provide attractive loan structures for eligible borrowers.
Flexible credit considerations
VA financing may provide additional flexibility compared with certain conventional programs.
Seller-paid costs
Depending on the transaction, seller concessions and credits may help reduce certain out-of-pocket costs.
Reusable benefit
VA home loan eligibility may be used more than once, depending on entitlement and eligibility.
A benefit you earned, turned into a place that's yours.
Use my VA benefit→Benefits described are general program features for eligible borrowers and are subject to entitlement, eligibility, underwriting, and program guidelines. Nothing here is an approval, pre-approval, or commitment to lend.
You served your country.Your home financingshouldn't feel complicated.
VA lending has unique rules, benefits, appraisal requirements, entitlement considerations, and closing structures.
Eileen helps break it down into a plan you can actually understand.
VA eligibility
Could you qualify for a VA loan?
Which best describes you?
Certificate of Eligibility
What's a Certificate of Eligibility?
Your Certificate of Eligibility, often called a COE, helps establish your eligibility for the VA home loan benefit.
Not sure where yours is? That's okay.
Eileen can help guide you through the next steps.
Certificate of Eligibility
Entitlement details
COEThe VA buyer journey
From military service
to a place of your own.
The VA homebuying process has a few unique steps. Eileen helps keep everything organized from beginning to end.
Talk with Eileen
Discuss your goals, timeline, income, current housing, and what you're hoping to buy.
Review VA eligibility
Understand your VA benefit and Certificate of Eligibility.
Build your financing plan
Review estimated buying power, payment, cash-to-close, and loan structure.
Get prepared to shop
Complete the appropriate loan review and pre-approval process.
Connect with a trusted agent
Need an agent? Eileen has trusted real estate professionals available in markets throughout the United States.
Find the right home
Shop confidently knowing your financing strategy.
VA appraisal + loan process
Navigate the VA-specific financing and appraisal process.
Closing day
Sign, close, and get the keys.
Home, and the keys to it.
A place of your own, financed with the benefit you earned.
Trusted agent network
Need an agent too?
We'll help you build the team.
Whether you're stationed somewhere new, relocating after service, or simply buying in a market you don't know well, Eileen can help connect you with trusted real estate professionals.
Trusted agent connections available in markets throughout the United States.
Where are you looking to buy?
Pick a region and Eileen will look into a trusted agent connection for that market.
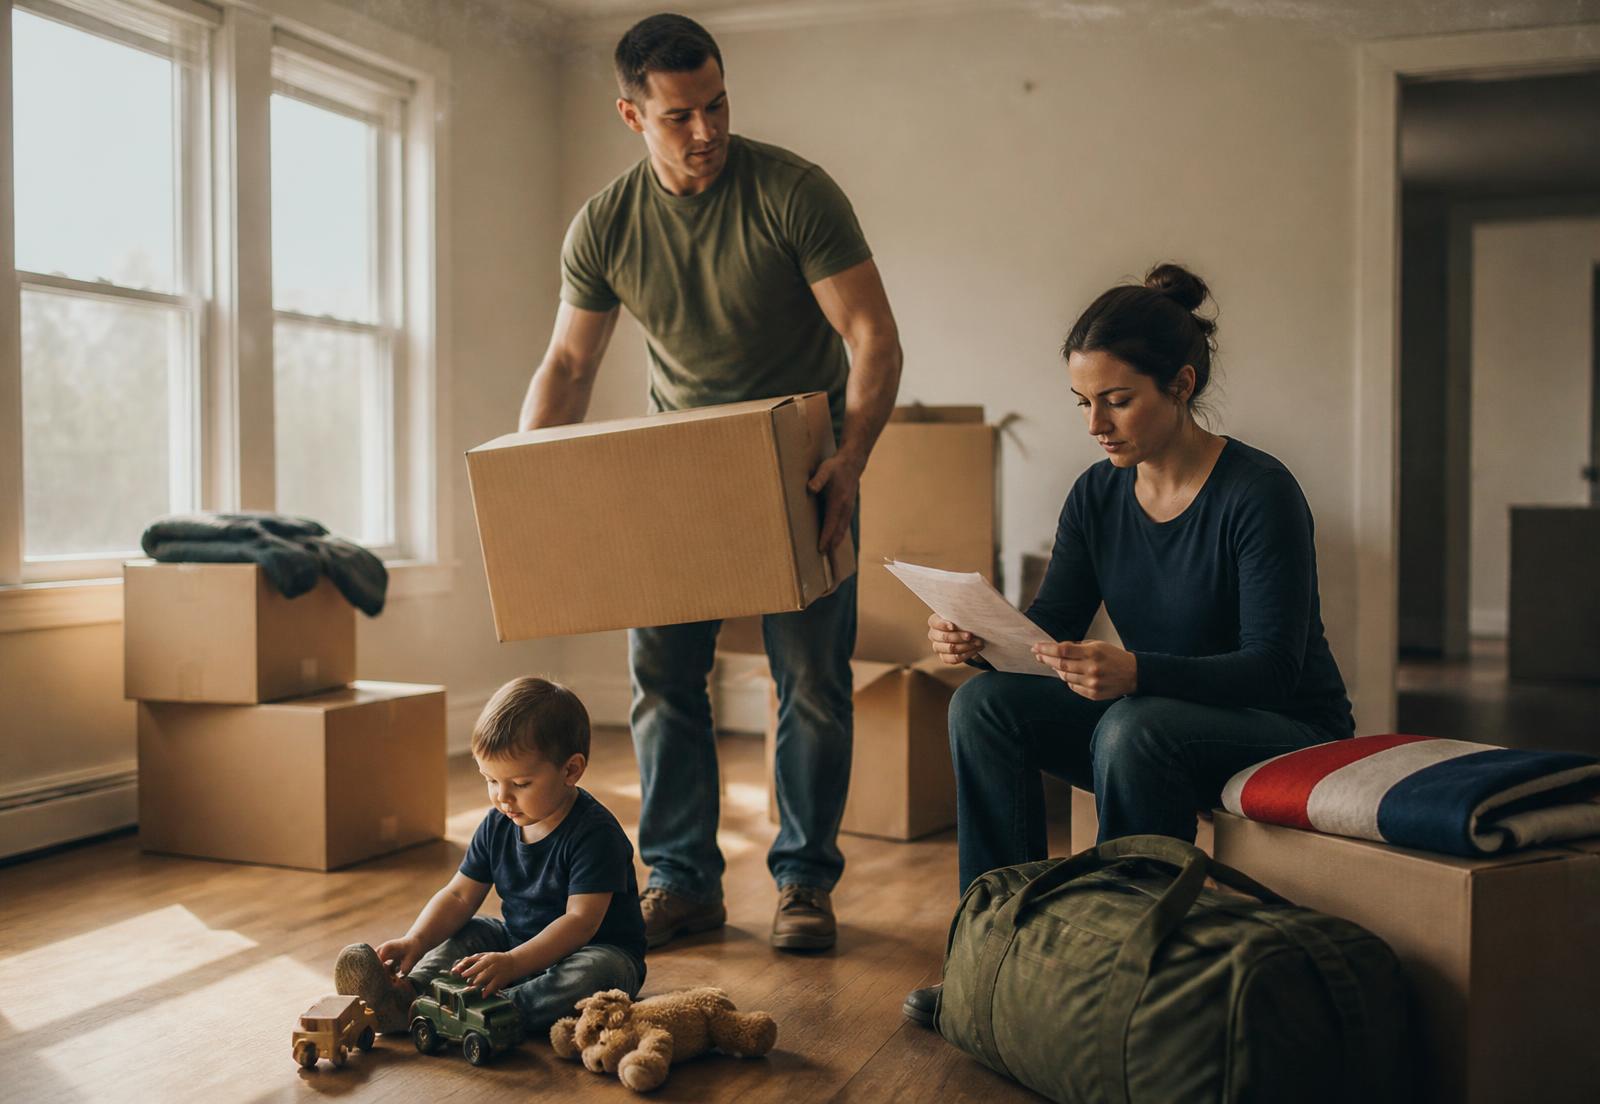
PCS move? New duty station? Coming home?
Military moves don't always happen on a convenient timeline.
Eileen can help buyers understand the financing side while a trusted local real estate agent helps with the search.
PCS relocation
Moving to a new duty station and need to understand your purchase options?
Transitioning out
Leaving active service and planning your next move?
Long-distance purchase
Buying in another city or state before you arrive?
The rate is only part of the VA loan strategy.
The bigger question is what the entire purchase looks like.
- 01Purchase price
- 02Monthly payment
- 03VA funding fee
- 04Seller credits
- 05Closing costs
- 06Down payment strategy
- 07Entitlement
- 08Property taxes
- 09Insurance
- 10Long-term plan
Eileen's take
“Don't just ask, ‘What's today's VA rate?’ Let's look at what the entire payment and transaction could look like for you.”
VA Market Pulse
A quick look at the mortgage market — and how VA buyers can approach it.
September 15, 2026 · Last updated: no live data source connected
Estimated VA market range
Available on request*
Estimated 30-year fixed
Available on request*
Estimated VA funding fee
Varies by entitlement*
Market headline
Rates moved higher today.
Eileen's strategy
“VA buyers should look beyond the headline rate. The structure of the offer and financing can matter just as much.”
Ways VA buyers are approaching today's market
Seller credits
The market changes — your strategy can too.
*Illustrative market information only. Rates and terms vary based on borrower qualifications, loan details, market conditions, and other factors. This is not a rate quote or commitment to lend. No live rate feed is currently connected.
Helping military buyers move forward with confidence.
Placeholder reviews shown for design purposes only. Verified client reviews will replace this content.
Your VA plan
Let's start your VA homebuying plan.
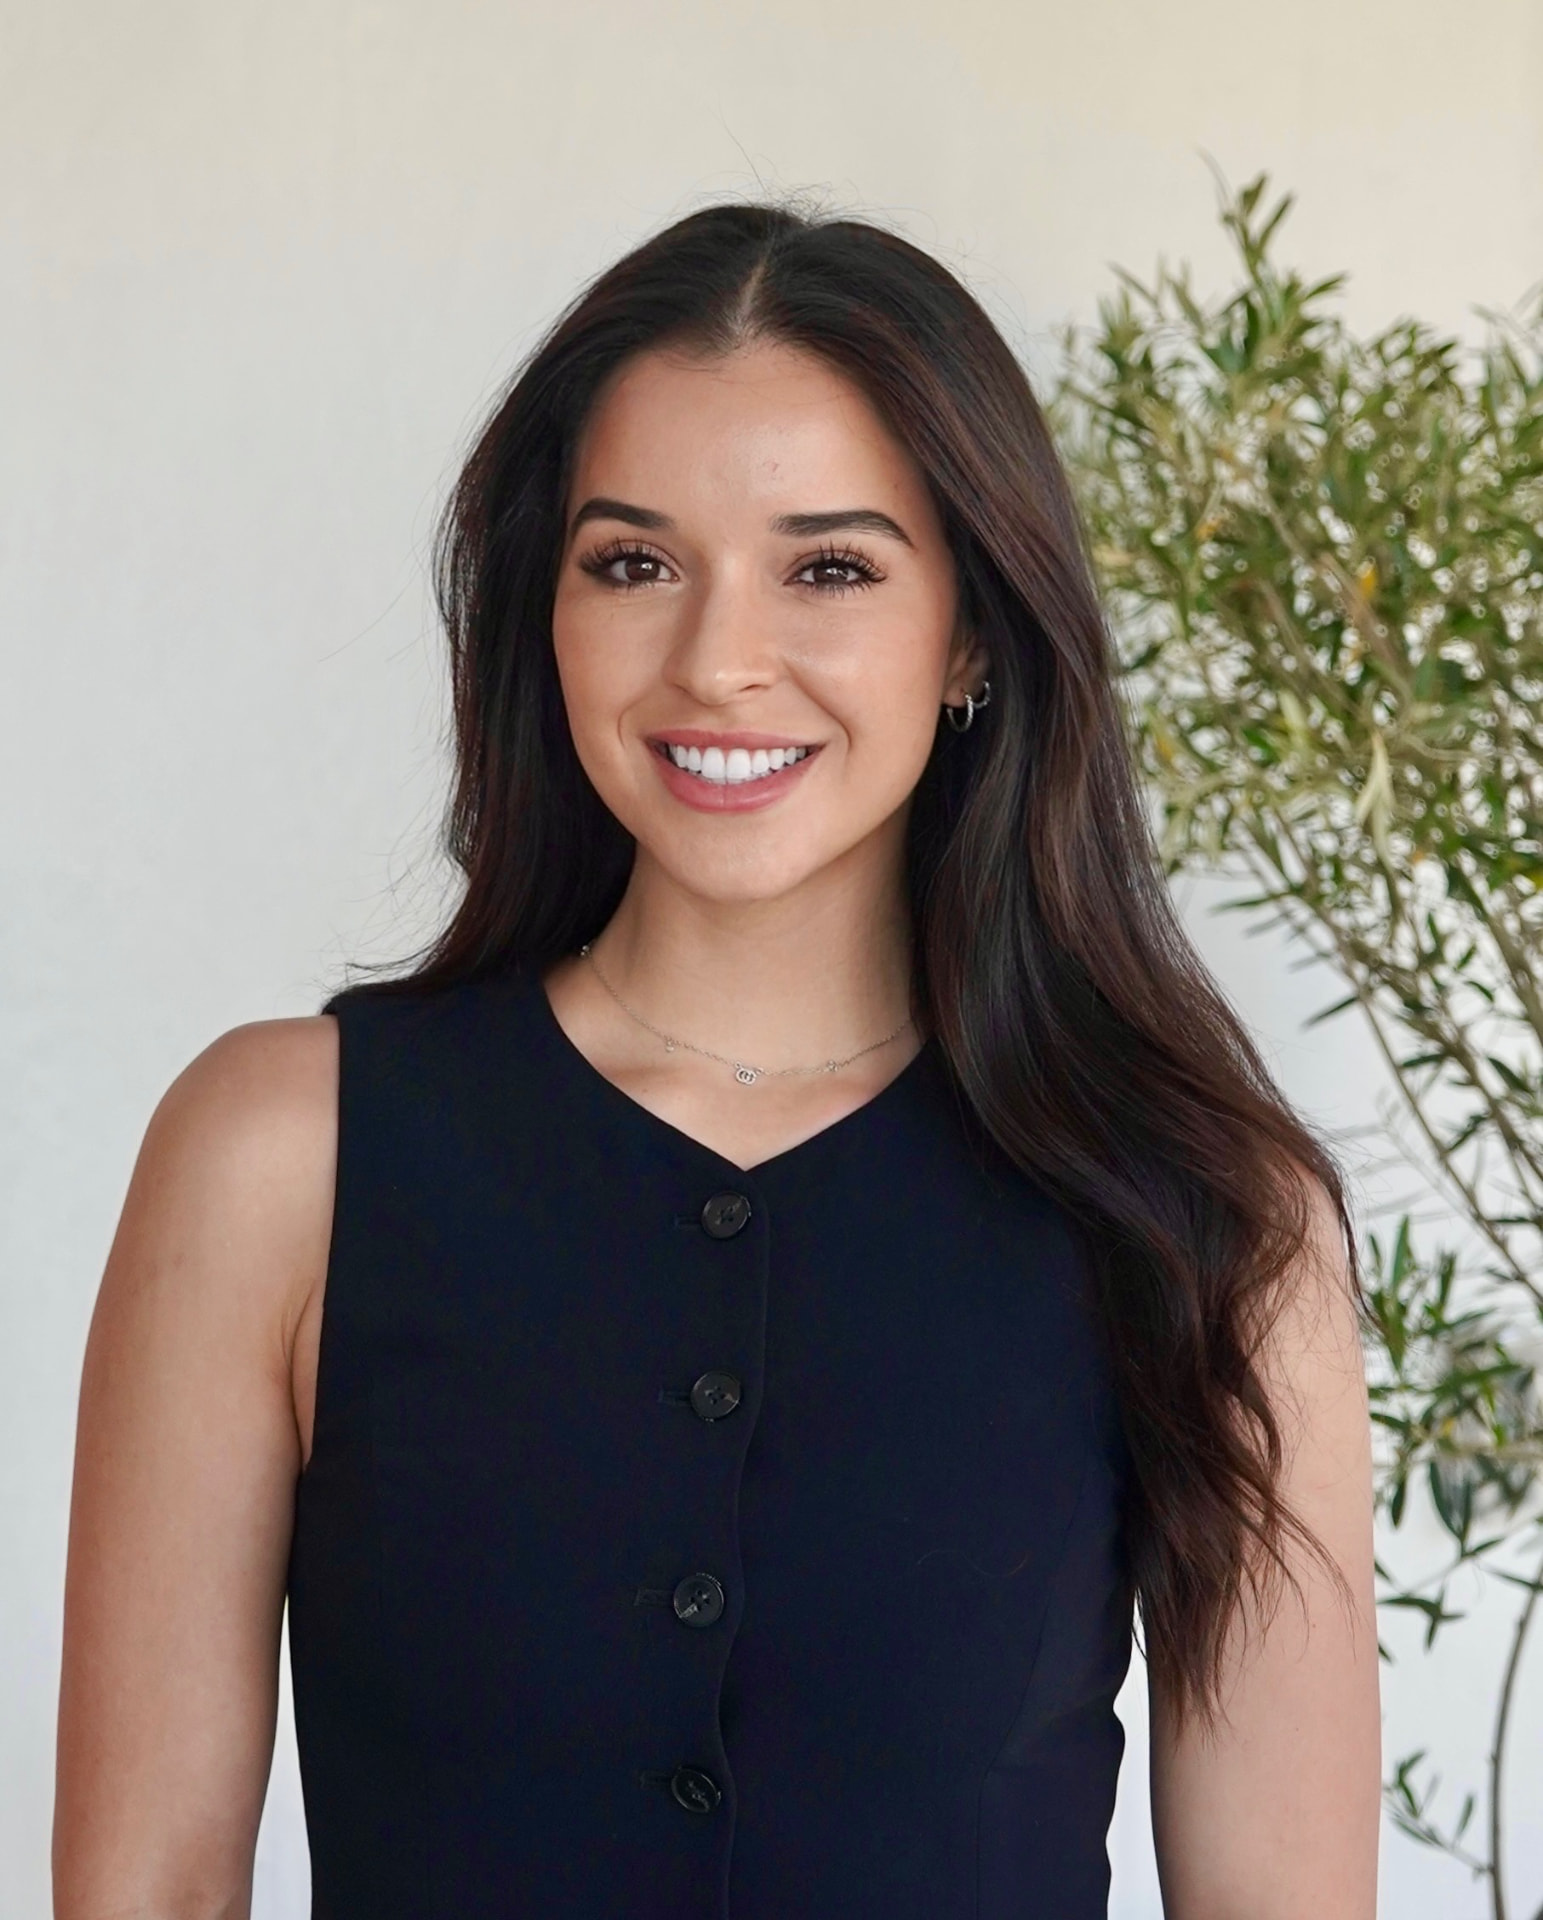
Meet Eileen
VA lending should feel personal.
Eileen helps veterans, active-duty service members, and military families understand their VA financing options and move forward with a clear plan.
Eileen Mirabal
Loan Officer · Exclusive Mortgage Company
NMLS 1587467
- VA home loan guidance
- VA pre-approval planning
- Certificate of Eligibility guidance
- Buying-power analysis
- Seller-credit strategy
- VA appraisal guidance
- Monthly-payment planning
- Trusted agent connections
Have a VA loan question?
Just text Eileen.
Message the same way you'd text a friend. No jargon — just a real conversation about what you're trying to do.
VA loan questions,
answered simply.
For many eligible VA borrowers, purchasing without a traditional down payment is possible. It still depends on entitlement, the purchase price, the property, and underwriting, so it's worth reviewing your specific situation before you assume either way.
In many cases, yes. VA home loan eligibility may be used more than once depending on your entitlement and how much of it is currently in use. Eileen can help you look at what may be available to you.
Entitlement is the portion of the VA benefit available to back your loan. How much you have available can affect your financing structure, so it's one of the first things worth reviewing.
The VA funding fee is a one-time fee associated with most VA loans that helps sustain the program. The amount varies based on factors like your service, down payment, and whether you've used the benefit before. Some borrowers may be exempt.
VA loans generally do not require monthly private mortgage insurance, which is one reason the payment structure can look different from other programs.
In many transactions, seller concessions and credits are possible. What's allowed depends on the program guidelines and what's negotiated in the purchase agreement.
There isn't one universal number. VA financing may allow additional flexibility compared with certain conventional programs, and guidelines vary by lender. Rather than guessing, Eileen can look at where you are today.
VA financing is intended for primary residences. Some buyers do use it for multi-unit properties they live in. If investment property is your goal, Eileen can walk through the options that may fit.
Sometimes. Condo projects generally need to meet VA requirements, so the specific building matters. It's a good idea to check before writing an offer.
In addition to value, the VA appraisal considers certain property condition and safety requirements. Eileen can help set expectations so surprises are less likely.
Active-duty service members may be eligible once service requirements are met. Eileen can help you review where you stand.
National Guard and Reserve members may be eligible depending on their service history and eligibility requirements.
Your Certificate of Eligibility, often called a COE, helps establish your eligibility for the VA home loan benefit. If you don't have yours yet, Eileen can help guide you through the next steps.
Eileen works with homebuyers throughout the United States, so buying in another state is a common conversation — especially for PCS moves and long-distance purchases.
If you need one, Eileen can help connect you with trusted real estate professionals in markets throughout the United States.
You earned the benefit.
Now let's put it to work.
Whether you are active duty, a veteran, or planning your next move after service, Eileen is here to help you understand your VA loan options and take the next step toward homeownership.
714.362.6087No pressure. Just clear answers and a plan.